Rolex Loan-to-Value Benchmarks: Reference Valuations & LTV Guide
Comprehensive benchmark data for borrowing against Rolex timepieces: secondary clearing prices, indicative advance rates across Daytona, Submariner, GMT, and Day-Date references.
Executive Summary & Key Takeaways
- Rolex sports models represent the most liquid collateral in the global luxury market, routinely qualifying for the maximum 80% LTV advance tier.
- Cerachrom bezel Daytonas and Pepsi GMT-Master II models command the highest advance predictability due to deep global dealer bids.
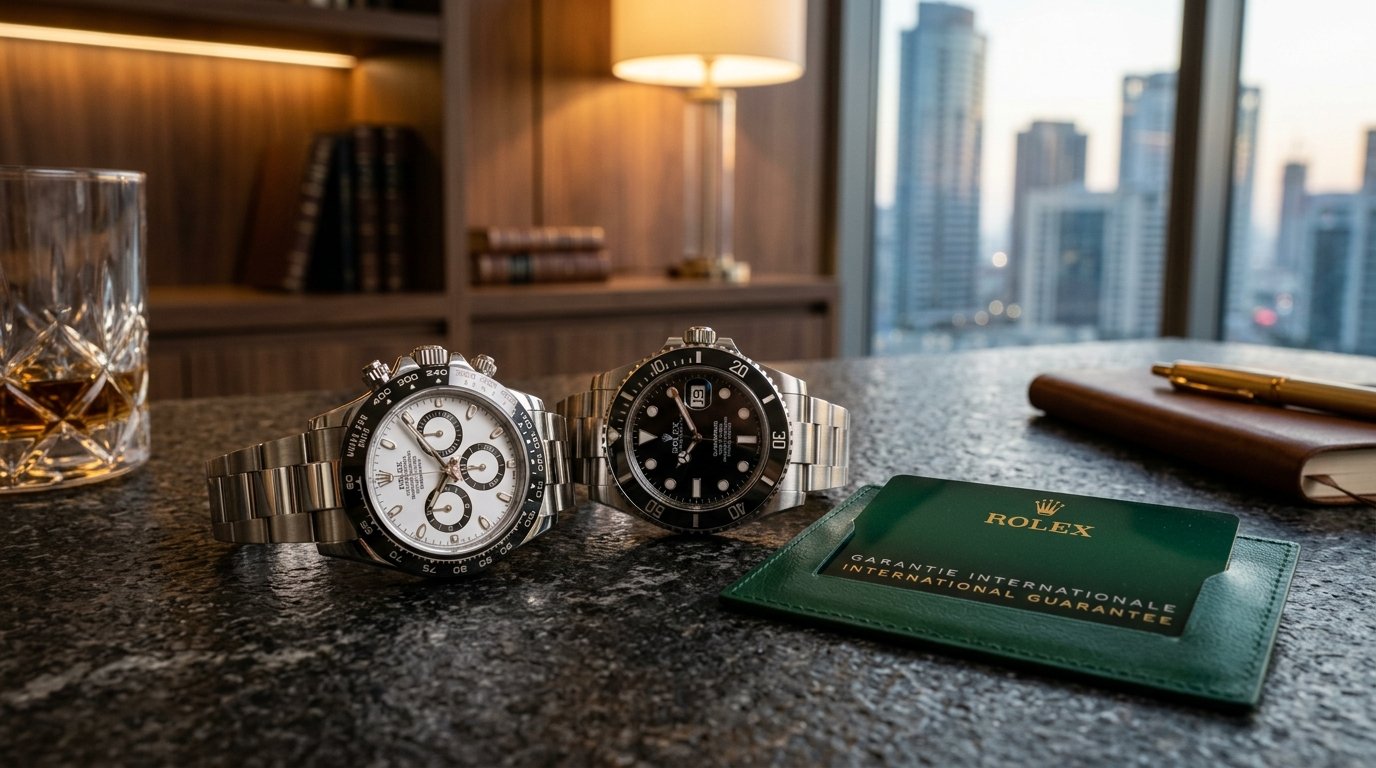
- Having the original Rolex guarantee card and box typically unlocks an additional 5% to 15% in advance capital compared to a naked watch.
- All Rolex collateral loans are non-recourse, requiring zero personal credit bureau checks or personal income documentation.
1. The Rolex Collateral Hierarchy: Liquidity Tiers
In the secondary watch market, Rolex represents the equivalent of blue-chip corporate bonds. However, not all Rolex references trade with equal velocity. In our private credit underwriting framework, models are classified into three distinct liquidity tiers:
Tier 1 (Highest Global Demand): Cosmograph Daytona (stainless steel & precious metal), GMT-Master II (ceramic bezel), and Submariner Date. These pieces exhibit the tightest bid-ask spreads worldwide and receive our top 80% LTV advance rates.
Tier 2 (Core Stable Liquidity): Sea-Dweller, Sky-Dweller, Datejust 41/36 (fluted/jubilee configurations), and Explorer II. These models trade consistently with established wholesale volumes, qualifying for 72% to 78% LTV advances.
Tier 3 (Precious Metal & Vintage Collector): Day-Date 36/40 in solid 18k gold and platinum, vintage 4-digit and 5-digit sport references (e.g., 1675, 5513, 1680). These pieces are appraised individually on intrinsic gold weight, dial originality, and verified provenance.
2. Current Rolex Lending Benchmarks (2026 Data)
The table below illustrates representative collateral loan metrics based on verified secondary wholesale clearing transactions:
| Rolex Model & Reference | Wholesale Clearing Range | Max LTV | Indicative Loan Advance | Monthly Rate Range |
|---|---|---|---|---|
| Cosmograph Daytona 116500LN (Black Dial) | $26,000 – $28,500 | 80% | $20,800 – $22,800 | 2.0% – 3.0% |
| Cosmograph Daytona 126500LN (Current Gen) | $29,000 – $32,000 | 80% | $23,200 – $25,600 | 2.0% – 3.0% |
| Submariner Date 126610LN (41mm Steel) | $12,800 – $13,600 | 80% | $10,240 – $10,880 | 2.0% – 3.5% |
| Submariner 'Kermit / Starbucks' 126610LV | $14,000 – $15,200 | 80% | $11,200 – $12,160 | 2.0% – 3.5% |
| GMT-Master II 'Pepsi' 126710BLRO (Jubilee) | $18,500 – $20,000 | 80% | $14,800 – $16,000 | 2.0% – 3.5% |
| GMT-Master II 'Batgirl' 126710BLNR (Jubilee) | $14,500 – $15,800 | 80% | $11,600 – $12,640 | 2.0% – 3.5% |
| Day-Date 40 228238 (18k Yellow Gold) | $36,000 – $39,000 | 78% | $28,080 – $30,420 | 2.0% – 3.0% |
| Datejust 41 126334 (Fluted / Jubilee / Blue) | $11,000 – $12,200 | 75% | $8,250 – $9,150 | 2.2% – 3.5% |
3. The Impact of 'Box & Papers' on Your Loan Offer
In Rolex collecting, documentation is paramount. A contemporary Rolex accompanied by its matching serialized green warranty card, green presentation box, instruction manuals, and serialized hangtags is considered a 'full set.'
A full set reduces wholesale dealer sales friction. Consequently, full-set timepieces receive up to 15% higher advance capital. If your watch is 'naked' (watch only), we still underwrite the loan, but the advance amount is calculated against the naked wholesale index.
Warranty Card Verification
The modern NFC-enabled green warranty card issued by authorized Rolex dealers contains an embedded microchip that our laboratory reads via near-field scanners, accelerating authentication.
4. Representative Loan Economics & Non-Recourse Terms
Loans against Rolex collateral are typically structured over 3, 6, or 12-month initial durations with flexible extension options. Borrowers incur zero origination fees, zero application charges, and zero depository storage costs.
Monthly interest rates reflect the borrower's capital tier (ranging from 2.0% to 3.5% monthly). Because the loan is 100% non-recourse, there are zero personal credit inquiries or personal liability guarantees required.
Related Guides & Articles
The Complete Guide to Borrowing Against Luxury Watches
Understand how collateral lending against luxury timepieces works without selling. Learn about LTV advance formulas, non-recourse legal protections, insured custody protocols, and avoiding predatory pawn terms.
How Watch Valuations Work: Wholesale Data, Condition & Mechanics
Discover the exact four-pillar framework horologists use to determine collateral loan values. Learn why retail appraisals are disregarded and how movement amplitude and unpolished chamfers impact loan offers.
Collateral Loan vs. Selling Outright: Capital Without Asset Surrender
Evaluate the financial trade-offs between selling your luxury watch and securing a non-recourse collateral loan. Compare dealer discounts, auction fees, tax liabilities, and future replacement costs.